Tilt: Cash Advance & Credit

Screenshots
Details
- Rating
- 101.34K reviews
- Version
- 7.23.1.792
- Developer
- Tilt Finance
Analysis by Norviv
When a bill lands before payday, I want to know what choices I have before I move money or borrow. That’s the situation where I’d look at Tilt: Cash Advance & Credit: a finance app from Tilt Finance that brings short-term cash options, credit products, score monitoring, saving and budgeting into one place. Its broad menu is useful, but it also means I’d approach it as a set of tools to compare carefully, not as an automatic fix for a tight month.
Start with the gap, not the offer
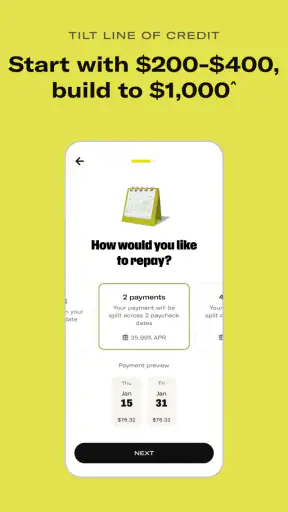
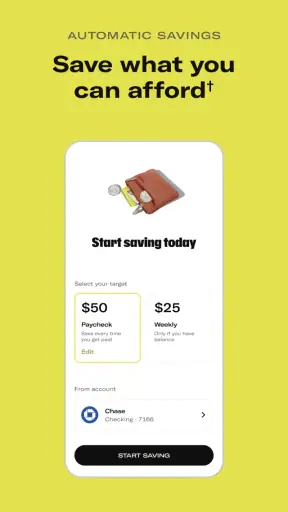
My first step would be to write down the amount I need, when I need it, and when I can realistically repay it. That simple check matters because a cash advance can solve a timing problem without solving the underlying budget problem. If the shortfall is recurring, I’d look at the saving and budgeting side of the app as well, rather than treating another advance as the default next move.
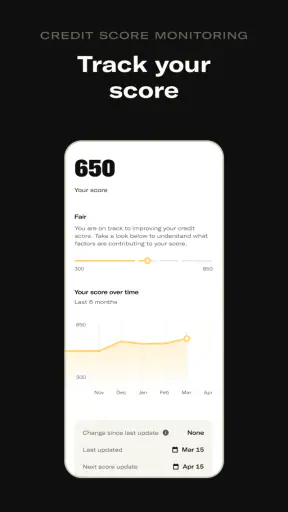
This is where the range of options can help. Cash advances and credit lines may suit different situations, while credit cards can be useful for purchases that I can pay off on schedule. Score monitoring adds another reason to check in, but seeing a score is not the same as improving it. I’d use the app to understand my position and make a plan, not assume that opening an account or borrowing will automatically strengthen my credit.
Move through the process with a repayment plan
After setting up an account, I’d review what Tilt makes available to me and read the terms attached to each choice before accepting anything. Eligibility can affect what a person can access, so I wouldn’t plan a bill payment around an amount I have not yet confirmed. If an option involves repayment, I’d check the due date against my next pay and regular expenses, then decide whether the remaining balance leaves enough room for essentials.
A realistic example: my utility bill is due a few days before payday, and I’m short because of an unexpected grocery expense. I’d compare the cost and timing of the choices shown in the app with asking the provider about a later payment date or using savings. If I chose an advance, I’d note the repayment date in my calendar and adjust my next week’s spending before taking the funds. That handoff—from checking an option in the app to making room for repayment in my own budget—is the part that prevents a temporary bridge from becoming a second shortfall.
Know where the app hands off
A finance app can organize decisions, but it cannot make the household trade-offs for me. Budgeting is most useful when I enter or review expenses honestly and use the result to spot what can wait. Saving works best as a habit built during less pressured weeks; it is harder to create a cushion while every spare dollar already has a job. I’d treat those tools as ongoing routines rather than features to open only when an emergency arrives.
Access to a bank account is part of the experience described in the original review, which noted that it is used to verify income. I would pause at that point and read the in-app explanations before connecting anything, especially if I’m cautious about financial privacy. The earlier review also described optional tips for an advance and no interest charges, but I would still inspect the current terms displayed to me. “No interest” does not mean every choice is automatically cost-free or right for every budget, and I would never select a tip without understanding how it affects the amount I keep.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Where it fits among money tools
Compared with a standalone budgeting app, Tilt’s appeal is that it puts borrowing-related choices alongside money-management tools and credit information. A budgeting-only alternative may be a better fit if I simply want to track spending and do not want to consider advances or credit products. A bank’s own app may be more convenient for someone who prefers to keep financial activity within an existing account, while a savings account is a better option when the expense can wait and I already have funds set aside.
I would also compare the app’s available terms with other ways to handle a cash-flow pinch. A bill provider may offer a payment arrangement; an employer may have a payroll option; and a low-cost loan or support from someone I trust could be more suitable in some circumstances. These alternatives are not interchangeable, so I’d compare total cost, timing, repayment obligations and consequences of missing a payment rather than choosing the fastest-looking button.
Who is likely to get the most from it
I can see this being useful for someone who has uneven timing between income and bills, wants several financial tools in one app, and is comfortable reviewing borrowing terms before acting. It may also suit a person who wants to check credit progress while building a more deliberate budget. Tilt is free to install, rated for Everyone, and has a 4.7 average from around 281,000 ratings; those figures suggest broad interest, but they cannot tell me whether a particular offer or repayment schedule will suit my circumstances.
I’d skip it if I’m looking for guaranteed cash, dislike linking financial information, or know that another repayment would leave me short again next month. It is also not a substitute for professional debt advice when bills are already overdue or borrowing is being used to cover borrowing. In those situations, contacting creditors, a nonprofit financial counselor or a trusted local support service may be a better first move than opening another credit option.
For an everyday workflow, I’d check the upcoming bill, inspect the choices Tilt presents, compare them with a payment extension or savings, and only then decide whether to proceed. Before closing the app, I’d record the repayment date and update my budget so the next paycheck is not silently committed twice. That small handoff from app to calendar and budget is easy to overlook, yet it is more useful than simply seeing that money is available.
First Impressions Matter
Opening Tilt for the first time, I was greeted by a sleek, user-friendly interface that didn’t overwhelm me with complicated jargon. The design is intuitive, which means even if you’re not a tech wizard, you’ll feel like you’ve got the hang of it in no time. The app is available on both Android and iOS, so no worries about compatibility here.
Features That Stand Out
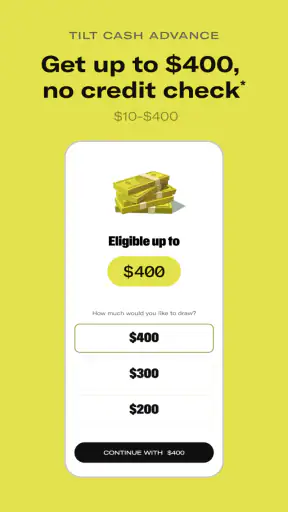
What really caught my eye was the simplicity of requesting a cash advance. You just need to set up your account, which takes a few minutes, and then you can request up to a certain amount depending on your eligibility. It’s fast, and the best part? No interest charges! Instead, Tilt operates on a tip-based system, which I thought was pretty cool and fair.
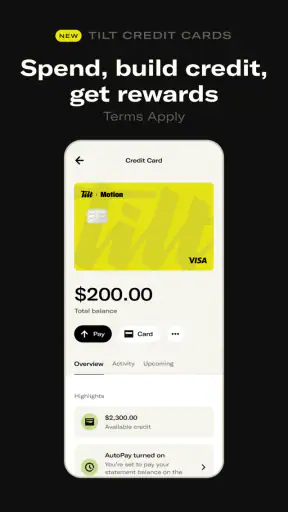
Another highlight is the credit-building feature. If you’re like me and always looking to improve that credit score, Tilt helps by reporting your payment history to major credit bureaus. It’s a win-win situation – you get the funds you need while also giving your credit a little boost.
Getting Down to the Nitty-Gritty
The app does require access to your bank account to verify your income, which might raise some eyebrows. However, Tilt assures users of top-notch security measures. Still, if you’re wary about privacy, it’s something to consider. On the plus side, the transparency around fees (or lack thereof) is refreshing. There are no hidden charges, just the optional tips.
Why I Keep Coming Back
For me, the convenience is unbeatable. Tilt has saved me from a couple of financial hiccups already, and the instant access to cash has been a lifesaver. Plus, knowing I’m not racking up high-interest debt every time I use it is a huge relief. It’s like having a safety net without the strings attached.
So, if you’re looking for a straightforward, no-nonsense app to help you through those tight spots, give Tilt a try. It might just become your new best financial friend. And hey, it’s always good to have options, right?
Small checks that make the experience safer
Before accepting an offer, I’d take a screenshot or note of the repayment details for my own records, then confirm the date and amount in the app itself. I’d also look at my account balance after accounting for rent, food, transport and any automatic payments. This is not about being overly cautious; it is a practical way to avoid counting the same paycheck toward two different obligations.
If I’m comparing a cash advance with a credit line or card, I’d compare the actual terms shown for my account rather than relying on a general impression of which product sounds cheaper. The amount available is only one part of the decision. Timing, repayment flexibility and what happens if plans change matter just as much. A smaller option that I can repay comfortably may be safer than taking the maximum simply because it appears on screen.
What to expect over time
Tilt has been available since December 4, 2017, and its current version is 7.23.1.792. It has more than five million installs, alongside around 101,000 written reviews. I take that as evidence that it is an established option many people have tried, not a promise that every user will qualify for the same products or have the same experience. I’d still judge it by the terms and tools presented to me and by how well they fit my own cash flow.
One question people often have is whether using a credit feature guarantees a score increase. I would not make that assumption. Credit outcomes depend on the activity being reported and the broader details in a person’s credit file; monitoring can help me stay aware, but it does not erase missed payments or make a high balance harmless. I’d check the explanation of any reporting feature in the app and keep paying all obligations on time wherever possible.
Another practical question is whether this is a good app for someone who only wants to save. It can still be worth exploring the saving and budgeting tools, but someone who wants nothing connected to advances or credit may prefer a simpler budgeting app or a dedicated savings account. The advantage here is having related tools together; the trade-off is that a wider financial menu can make it easier to get distracted by borrowing when the real need is a spending plan.
Overall, I’d treat Tilt as a useful place to review options when cash flow gets awkward, not as a standing source of extra income. Its mix of advances, credit products, score monitoring, saving and budgeting can help me make a more informed choice, provided I slow down at the point where an offer turns into a repayment. If I keep the amount tied to a clear need, check the terms, and make room for the money to leave my next budget, the app has a practical role. If I cannot see a reliable way to repay, I would close it and look for a different solution first.
Frequently Asked Questions
01What is Tilt: Cash Advance & Credit, and how does it work?
Tilt is a financial app designed to provide users with quick access to cash advances and credit management tools. It offers a seamless interface for requesting short-term loans, tracking expenses, and managing credit scores. Users can apply for advances directly through the app, which assesses eligibility based on their financial profile.
02Is Tilt safe to use for financial transactions?
Yes, Tilt employs industry-standard security measures to protect users' personal and financial information. The app uses encryption and secure servers to ensure data safety. Additionally, Tilt is compliant with financial regulations, providing users with peace of mind when conducting transactions and managing their finances.
03Are there any fees associated with using Tilt?
While downloading the Tilt app is free, fees may apply depending on the services used. Cash advances typically incur a small fee or interest rate, which is clearly outlined before acceptance. It's essential to review the terms and conditions within the app to understand any potential costs associated with its use.
04How quickly can I receive a cash advance through Tilt?
Tilt is designed for speed and convenience, often providing cash advances within minutes of approval. The app's automated systems assess applications promptly, and once approved, funds are transferred directly to the user's bank account, making it a reliable option for urgent financial needs.
05Can I improve my credit score using the Tilt app?
Yes, Tilt offers tools to help users improve their credit scores over time. The app provides insights on credit utilization, payment history, and other factors that influence credit ratings. It also offers personalized tips and reminders to help users stay on track with their financial goals.


